Europe Required More Than Vehicle Access
An Asia-based EV manufacturer was assessing how to establish a durable position in Europe. The decision was not limited to launching vehicles or appointing distributors. It concerned whether the client could build a competitive operating position across trade exposure, pricing, charging, service, supply chains, connected-vehicle data and customer expectations.
Direct exports offered a rapid route into the market. But an export model could remain exposed to cross-border cost, policy, logistics and local-capability constraints. Deeper local commitments could strengthen responsiveness and industrial presence, while creating fixed capital, utilisation and execution risk. The central question was how to enter Europe without committing to an operating model before the conditions required to sustain it were proven.
The Decision Was Export, Localise or Partner
The client was considering direct exports, local assembly, joint ventures, acquisition, greenfield manufacturing and phased hybrid pathways. Each option changed the balance among speed, capital, trade sensitivity, local control, customer access and future flexibility.
Export-led entry could preserve capital and accelerate launch, while increasing exposure to landed-cost pressure, transport, trade changes and limited local operating depth. Assembly or manufacturing could alter selected logistics, supply and policy exposures, but depended on credible utilisation, workforce, site, energy, supplier and quality conditions.
Partnership offered a third route. Local distributors, contract manufacturers, charging operators, service providers, financial institutions and technology partners could accelerate market access. They could also affect control of the brand, customer relationship, data architecture, vehicle lifecycle and long-term economics. The relevant decision was not which route was intrinsically superior, but which combination could remain credible as conditions changed.
Entry Sat Within a Wider Operating System
A conventional market-entry study could assess demand, price segments, competitors and distribution. Those inputs were necessary, but they could not establish whether a European position would remain competitive under changing trade, industrial and digital conditions.
Trade treatment shaped delivered cost, pricing and the viability of an export-led model. Local production could reduce selected exposure, but could not independently establish competitiveness. Manufacturing value depended on whether the wider operating system—suppliers, components, batteries, logistics, labour, energy, permitting, quality systems and service capability—could support it at the required scale.
Customer demand depended on the same system. Charging conditions affected whether customers could charge reliably at home, on corridors, at destinations and through public networks. Service coverage, financing, insurance, maintenance, resale confidence and digital experience influenced whether an attractive vehicle proposition could translate into sustained adoption across target segments and markets.
Connected-vehicle governance added a further dependency. Data access, sharing obligations, privacy, cybersecurity, cloud architecture and aftermarket rights could affect the OEM’s control over service, customer experience and the economics of the vehicle lifecycle.
Local Presence Had to Become Capability
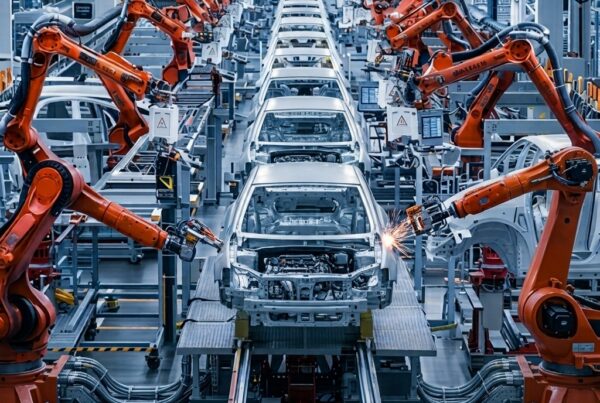
Local assembly or manufacturing was not simply a response to trade conditions. It was a decision to establish an operating capability that could connect product configuration, suppliers, service, data, local partnerships and customer feedback.
A deeper European presence could improve coordination with customers and partners, support faster market adaptation and create a platform for selected engineering, software, charging or financing relationships. It could also create dependencies on site readiness, utilities, industrial relations, supplier performance, component qualification, working capital and the ability to sustain output.
The key distinction was between local production and a local operating system. Manufacturing created strategic value only where supplier, workforce, quality, service, data and utilisation conditions could support it. Without those conditions, a plant could add fixed exposure without improving the client’s long-term market position.
Testing Entry Paths Under Change
Bruqe framed the engagement around target segments, market-access objectives, investment limits, local-control requirements, trade exposure and acceptable dependencies. The work mapped how pricing, trade conditions, local production, battery and component supply, charging, service, finance, data governance, customer adoption and partner incentives affected one another.
It then tested export, assembly, partnership, acquisition, greenfield and hybrid pathways across plausible futures for trade and pricing, charging and service maturity, local-investment expectations, supply-chain conditions, data requirements, demand, manufacturing economics and competitor response.
The purpose was not to select a permanent route to Europe. It was to identify which early actions built customer access and operating knowledge, which capabilities required local control, where partnership accelerated progress, and which conditions justified deeper manufacturing or capital commitment.
Building Evidence Before Scale
The analysis separated early, evidence-building commitments from later commitments that required validated demand and operating readiness. Country and segment selection, distribution, service, charging relationships, finance, data architecture and selected local partnerships could establish a credible market presence without immediate full-scale manufacturing investment.
This created explicit decision gates. Sustained demand, pricing resilience, trade conditions, charging and service readiness, partner performance, battery and component access, site economics and expected utilisation each informed whether the client should expand exports, localise selected capabilities, deepen a partnership, establish assembly or commit to manufacturing.
The resulting approach preserved flexibility while ensuring that local operating capability could develop ahead of irreversible scale commitments.
Keeping European Growth Adaptable
The resulting decision architecture connected market access to the wider commercial, industrial, digital and service system required to sustain it. It enabled the client to pursue European growth while preserving the ability to scale, partner, localise or redesign as conditions resolved.
The enduring implication was clear: a durable European EV position is not created by exporting vehicles or building a plant in isolation. It depends on whether the operating system around the entry model can remain competitive over time.